IMPORTANT ANNOUNCEMENT FOR ALL MEMBERS
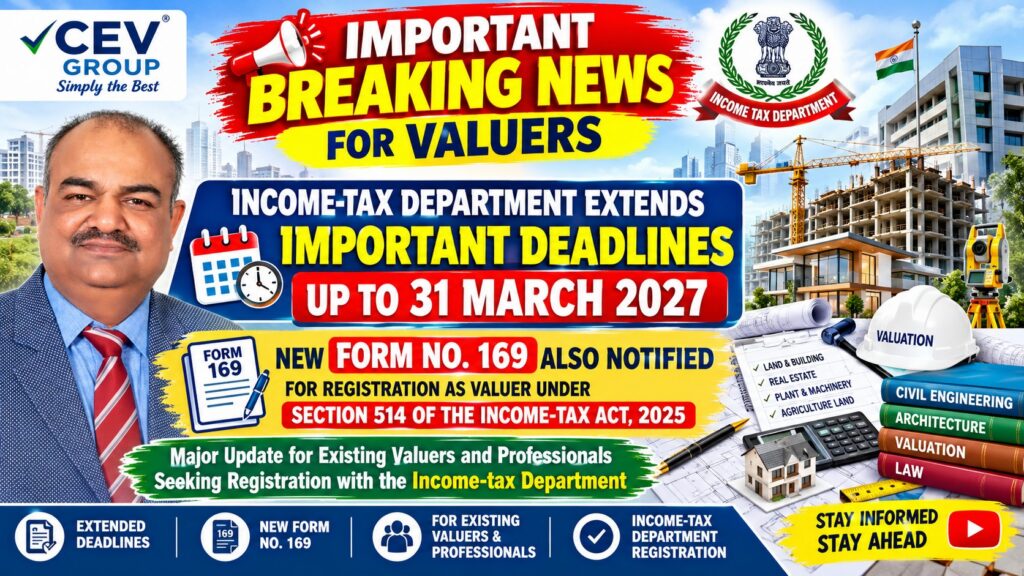
🚨 IMPORTANT BREAKING NEWS FOR VALUERS
INCOME-TAX DEPARTMENT EXTENDS IMPORTANT DEADLINES UP TO 31 MARCH 2027
The notification dated 17 September 2026 is significant for valuers because it extends the relevant deadlines under Rules 246 and 256 and, importantly, substitutes Form No. 169 for registration as a valuer under Section 514 of the Income-tax Act, 2025. The notification is Income-tax (Fourth Amendment) Rules, 2026, Notification No. 120/2026.
NEW FORM NO. 169 ALSO NOTIFIED FOR REGISTRATION AS VALUER UNDER SECTION 514 OF THE INCOME-TAX ACT, 2025
Major Update for Existing Valuers and Professionals Seeking Registration with the Income-tax Department
The Central Board of Direct Taxes (CBDT), Ministry of Finance, Department of Revenue, Government of India, has issued Notification No. 120/2026 – Income-tax (Fourth Amendment) Rules, 2026, dated 17 September 2026, further amending the Income-tax Rules, 2026.
The notification has brought important changes concerning the registration of valuers under Section 514 of the Income-tax Act, 2025, including an extension of the relevant date from 30 September 2026 to 31 March 2027 and substitution of Form No. 169.
This development is particularly relevant to existing valuers who are required to transition/register under the new Income-tax framework.
Dear Esteemed Members,
The Council of Engineers & Valuers (CEV Group) has always remained committed to supporting its members by providing timely guidance, practical resources, and professional assistance in complying with the latest statutory requirements.
With the introduction of the Income-tax Act, 2025 and the corresponding Income-tax Rules, 2026, valuers seeking transition of registration as Valuers under the Income-tax Department are required to submit Form No. 169 along with various supporting documents and annexures.
🔴 KEY UPDATE AT A GLANCE
30 SEPTEMBER 2026 → 31 MARCH 2027
The notification substitutes “31st March, 2027” for “30th September, 2026” in:
Rule 246(4)
The date specified in Rule 246(4) has been extended from 30 September 2026 to 31 March 2027.
Rule 256(4)
The date specified in Rule 256(4) has similarly been extended from 30 September 2026 to 31 March 2027.
Accordingly, the extension provides additional time under the amended Rules until 31 March 2027.
🟢 NEW FORM NO. 169 NOTIFIED
One of the most important changes introduced through the notification is the substitution of the earlier Form No. 169 with a new Form No. 169.
The revised form is prescribed for:
Application for registration as a valuer under Section 514 of the Income-tax Act, 2025.
The new Form No. 169 specifically refers to Rules 246 and 247.
This revised Form No. 169 should therefore be carefully noted by all professionals preparing applications for registration as valuers under the new Income-tax Act.
📋 IMPORTANT DETAILS IN THE NEW FORM NO. 169
The substituted Form No. 169 contains several important sections requiring applicants to furnish personal information, asset-class information, qualifications, experience and declarations.
PART A – PERSONAL INFORMATION
The applicant is required to provide, among other particulars:
- Full Name
- Permanent Account Number (PAN)
- Address
- Date of Birth
- Mobile Number
- Email ID
The notification specifically provides that the first, middle and last names should be furnished in full and without abbreviations.
The address requirements have also been specified in detail, including country/region, flat/door/building, road/street/block/sector, PIN/ZIP code, post office, area/locality, district and state. The address may also contain DIGIPIN.
🏢 PART B – CLASS OF ASSET
The applicant has to specify the class of asset for which registration as a valuer is being sought.
The notification provides the following classes of assets:
- Immovable property, other than agricultural lands, plantations, forests, mines and quarries
- Agricultural lands, other than coffee, tea, rubber or cardamom plantations
- Coffee, tea, rubber or cardamom plantations
- Forest
- Mines and quarries
- Stocks, shares, debentures, securities, shares in partnership firms and business assets, including goodwill, subject to the exclusions specified in the Form
- Machinery and plant
- Jewellery
- Works of art
- Life interest, reversions and interest in expectancy
- Any other asset
⚠️ IMPORTANT
The notification specifically states that a separate Form is required to be filled up for registration for different classes of assets.
Members should therefore carefully identify the appropriate asset class applicable to their proposed registration.
🎓 PART C – QUALIFICATIONS AND EXPERIENCE
The new Form No. 169 requires detailed information relating to the applicant’s eligibility as a valuer.
The Form includes:
Educational Qualifications
Details of educational qualification(s) are to be provided/uploaded.
Former Employment
Details relating to former employment are required.
Professional Practice
Details of practice as:
- Consulting Engineer
- Valuer of Real Estate
- Surveyor
- Architect
- etc.
are required to be furnished.
Other Eligibility Details
Applicants may also be required to furnish any other details relevant to establishing eligibility as a valuer.
Experience During the Last Three Years
The Form specifically requires the applicant to enclose full details of experience as a valuer, including a list of assets valued or works executed during the last three years.
Members should therefore start compiling their relevant experience records, valuation assignments and supporting documents well in advance.
📑 WEALTH-TAX REGISTRATION
The new Form also asks whether the applicant is already registered as a valuer under the Wealth-tax Act, 1957.
Where the answer is yes, the applicant is required to upload the valid certificate of registration.
⚖️ DISQUALIFICATION / ELIGIBILITY DECLARATION
The Form requires the applicant to state whether he or she is disqualified from applying for registration by reason of any provision contained in Rule 247(4) or 247(5).
Where applicable, the relevant clause is required to be specified.
Members should therefore carefully examine the applicable eligibility and disqualification provisions before submitting their applications.
✍️ VERIFICATION AND PROFESSIONAL DECLARATION
The revised Form No. 169 contains a specific declaration by the applicant.
The applicant declares, among other matters, that he/she shall:
- Make an impartial and true valuation of assets required to be valued;
- Furnish the valuation report in the prescribed form;
- Charge fees at rates not exceeding the rates prescribed by the Board; and
- Not undertake valuation of an asset in which the applicant has a direct or indirect interest.
These declarations should be carefully read and understood before the Form is submitted.
💰 APPLICATION FEE
The notification states that Form No. 169 must be accompanied by a fee of ₹10,000.
However, no fee is required where the valuer is already registered under the Wealth-tax Act, 1957.
Members are advised to verify the applicable payment procedure and current filing requirements before submission.
🟡 SOME INFORMATION MAY BE PRE-FILLED
An important facilitation provided in the revised Form is that:
“Some of the information in the form would be pre-filled to the extent possible.”
Applicants should nevertheless carefully check all pre-filled information and ensure that the final application contains complete and accurate particulars.
📢 SPECIAL MESSAGE TO CEV MEMBERS
In view of this latest notification, the Council of Engineers & Valuers (CEV Group) advises all members who are required to obtain registration/transition under the new Income-tax framework to:
1. DO NOT WAIT UNTIL THE LAST DATE
Although the relevant date has now been extended to 31 March 2027, members are advised to utilise the additional time to prepare their applications properly.
2. REVIEW THE NEW FORM NO. 169
The Form has now been substituted by the Income-tax (Fourth Amendment) Rules, 2026.
Members should use the latest applicable Form No. 169 rather than relying blindly on an earlier version.
3. PREPARE YOUR SUPPORTING DOCUMENTS
Members should organise their:
- Educational qualification documents
- Employment records
- Professional practice details
- Valuation experience
- Details/list of assets valued or works executed during the last three years
- Existing Wealth-tax registration certificate, wherever applicable
- Other documents relevant to establishing eligibility
4. VERIFY THE ASSET CLASS
Members should carefully determine the appropriate class of asset for which registration is being sought.
5. REVIEW THE ELIGIBILITY AND DISQUALIFICATION PROVISIONS
Particular attention should be given to the requirements referred to in Rule 247(2), 247(4) and 247(5).
📚 CEV MEMBER SUPPORT INITIATIVE
The Council of Engineers & Valuers has already undertaken a professional facilitation initiative for the benefit of its members by preparing an editable Word version of Form No. 169, together with a filled sample Form and sample Annexure formats for ready reference.
In view of the substitution of Form No. 169 through the latest notification, members are advised to ensure that they use the updated version corresponding to the latest notified Form.
The sample annexures are intended only as reference material and may be suitably modified according to the individual facts, qualifications, experience and requirements applicable to each applicant.
⚠️ IMPORTANT: READ THE NOTIFICATION CAREFULLY
The extension of the date should not be interpreted as eliminating any other requirement under the Income-tax Act, 2025 or the Income-tax Rules, 2026.
Members should carefully examine the complete notification and the applicable statutory provisions before filing their applications.
The notification also makes other amendments to the Income-tax Rules, including amendments relating to Rules 160, 176 and 225. These changes are separate from the specific provisions concerning the registration of valuers.
🏛️ OFFICIAL NOTIFICATION
The notification is:
Notification No. 120/2026
F. No. 370142/30/2026-TPL
Income-tax (Fourth Amendment) Rules, 2026
Dated: 17 September 2026
Ministry of Finance, Department of Revenue, Central Board of Direct Taxes
The notification records that the Income-tax Rules, 2026 were originally published on 20 March 2026 and were last amended before this notification by Notification G.S.R. 656(E), dated 24 July 2026.
🔔 CEV ADVISORY
31 MARCH 2027 IS THE EXTENDED DATE — BUT EARLY PREPARATION IS STRONGLY ADVISED
The extension provides additional time for valuers and other eligible professionals to complete the necessary process.
Members are advised to use this additional period constructively by:
UNDERSTANDING → PREPARING → VERIFYING → SUBMITTING
their applications and supporting documentation in accordance with the applicable provisions.
COUNCIL OF ENGINEERS & VALUERS (CEV GROUP)
Professional Support • Knowledge • Guidance • Valuation Excellence
For the benefit of the valuation fraternity
CEV Group – Simply the Best
Registration under the Income-tax Act, 2025 – Immediate Action Required Before the Statutory Deadline
Do Not Wait Until the Last Date – Complete Your Registration/Updation in Time
Issued to all members in the Interest of the Valuation Profession
Do Not Rely on Rumours or Unverified Information
Members are advised not to rely upon WhatsApp messages, social media posts, YouTube videos, unofficial announcements, or speculative interpretations regarding the registration process or the proposed Valuer Examination under the Income-tax Act, 2025.
Only information issued through the Income-tax Department, statutory notifications, or authentic professional advisories should be considered reliable.
The recent RTI clarification obtained from the Income-tax Department has reaffirmed that several procedural matters are presently being handled administratively. Accordingly, members should exercise due diligence and strictly comply with the prescribed statutory requirements.
1. Filing of Form No. 169 – The Most Important Compliance
Every applicant is required to complete Form No. 169 carefully and accurately.
Applicants should ensure that all particulars are correctly furnished before submission.
Particular attention should be paid to:
- Full personal particulars
- Category of valuation asset
- Registration details
- Address and jurisdiction
- Contact information
- Disclosure of the Registered Valuer Organisation (RVO) of which the applicant is a member, wherever applicable.
No Recommendation from the RVO is Required
Members should note that no recommendation, forwarding letter, verification certificate or approval from the Registered Valuer Organisation is required while submitting Form No. 169.
However, applicants are advised to attach all relevant supporting documents wherever necessary to substantiate the declarations made in the application.
Proper documentation helps avoid unnecessary correspondence and delays during verification.
2. Existing Wealth-tax (Rule 34AB) Registered Valuers – Updation is Mandatory
All valuers holding a valid certificate of registration under Rule 34AB of the Wealth-tax Act/Rules as on 31 March 2026 are required to update their registration under the Income-tax Act, 2025.
The application should be submitted either personally or through Speed Post/Registered Post to the jurisdictional Principal Chief Commissioner of Income Tax (CCIT).
No Government Fee Payable
One significant relief provided under the Rules is that no government fee is payable for updation by existing registered valuers.
Members should therefore complete the updation process without delay.
Issued in the larger interest of the valuation profession
Council of Engineers & Valuers (CEV Group)
“Committed to Professional Excellence, Ethical Practice and Statutory Compliance.”
CLICK THE BUTTON FOR ALL DETAILS
VIEW FULL VIDEO
Published by: Council of Engineers and Valuers (